Market updates
Weekly Rate Tracker 10/21/2026
 Frank EllerbroekMortgage Broker · NMLS #128726Vantage Mortgage Brokers · NMLS #35986Published 2 min read
Accessibility
Market updates
Frank EllerbroekMortgage Broker · NMLS #128726Vantage Mortgage Brokers · NMLS #35986Published 2 min read
DATE: October 21st, 2026
STATES: IDAHO, WASHINGTON AND OREGON
CHANGE THIS WEEK: SLIGHT IMPROVEMENT/STAGNANT (since last Wednesday)
SUGGESTION: LOCK
Mortgage Rates Finally Dip—But Will It Last?
Mortgage rates offered a little relief this week, posting their first decline in more than two months. But by Wednesday afternoon, rates were edging higher again—a reminder that a weekly improvement can include plenty of daily ups and downs.
The Mortgage Bankers Association reported its average 30-year fixed rate fell from 7.50% to 7.41%, while mortgage applications dropped 5.3%. Buyers are still feeling the pressure of higher borrowing costs, even with this modest improvement. These are national survey averages; your options will depend on your loan details and lender pricing.
What’s moving the market? Inflation, employment and the bond market remain the key drivers. Wednesday afternoon’s weaker demand for a Treasury bond auction added upward pressure to rates. Investors are also weighing wholesale inflation data, upcoming jobless claims, leading economic indicators and consumer sentiment as they prepare for the next Federal Reserve meeting.
The Fed’s decision will matter, but it doesn’t directly set mortgage rates. Mortgage pricing can move before the meeting as investors adjust their expectations for inflation and the economy.
What does this mean for you? A small dip is encouraging, but it is too early to call it a lasting turnaround. If you’re shopping for a home or approaching a closing date, stay in close communication with me so we can review current pricing and your lock options.
My website’s Live Rates feature is also an easy place to start—no personal information required.
Interest Rate Pricing Options*
(rates subject to change)
MONTHLY PAYMENTS: This reflects Principal and Interest (P&I) on Conventional and also including PMI on FHA. Taxes and insurance not included, but need to be factored in housing payments and budget as these can vary by property. A VMG Mortgage Broker can run an analysis anytime by request.
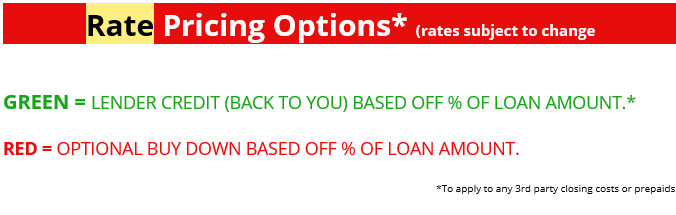
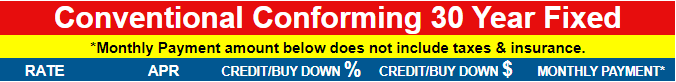
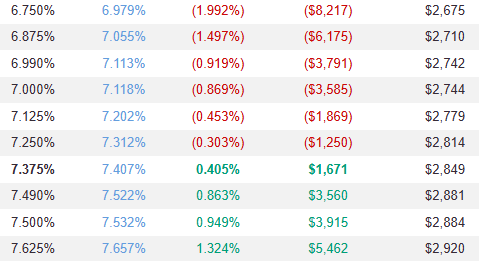
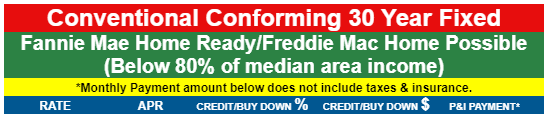
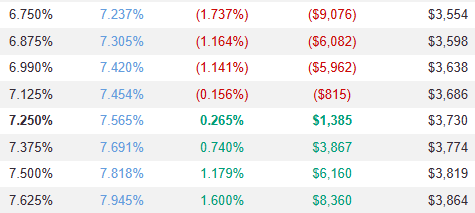
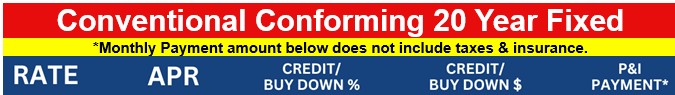
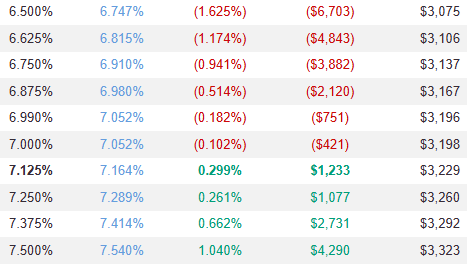
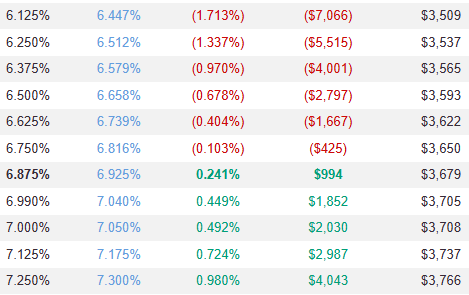
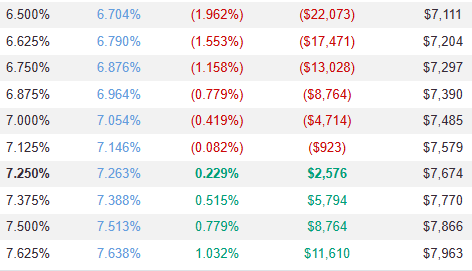
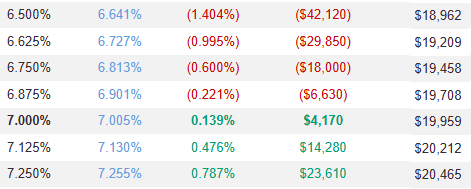
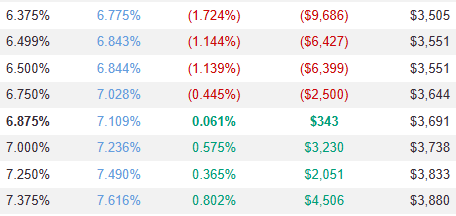
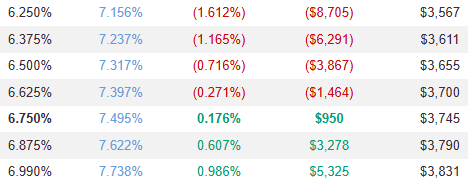
*Rates are subject to change. Conforming conventional interest rate samples based on a $550,000 purchase price, $412,500 loan amount, 25% down, 740 FICO score, with impounds on a 30-day rate lock period and $1150 underwriting fee if not covered by lender rebates. FHA is based on a $550,000 purchase price, $530,750 base loan amount and a 3.5% down payment, but other same variables. This pricing engine reflects the most favorable results after comparing our network of wholesale lending partners. This pricing engine does not include any other applicable 3rd party title and escrow charges, appraisal, credit report, or prepaid tax and insurance reserves. The displayed annual percentage rates (APRs) include total points and additional prepaid finance charges but do not include other closing costs. Loan pricing may only be locked through a VMB home loan consultant to be effective after a formal loan application. Rates will depend in part on your unique credit history and transaction characteristics. Monthly payments include principal, interest, and PMI if applicable, but do not taxes and insurance. This is not a formal Loan Estimate (LE). A Loan Estimate is provided and can be requested pursuant to Federal regulations and with a formal loan application. This information does not constitute a loan commitment or approval.
Tell Frank what you’re trying to do. He’ll shop 35+ wholesale lenders and show you the options side by side.
This article is general information, not a Loan Estimate, a commitment to lend or financial advice for your specific situation. Rates and programs change; confirm the details with Frank before you act. Frank Ellerbroek, NMLS #128726, Vantage Mortgage Brokers, NMLS #35986.
Market updates2 min read
Weekly Rate Tracker: Mortgage Rates Ease Again, but Inflation Keeps Markets on Edge
Market updates3 min read