
Related video
How to Shop Mortgage Rates & Fees (Must Watch)
How to read live rates, what lender credits and discount points mean, and how to compare offers fairly.
Watch on its own pageWhen does a Lake Oswego purchase need a jumbo loan?
When the loan amount is above the 2026 conforming limit of $832,750 for a one-unit home, which applies in Clackamas County and everywhere else in Oregon. Price alone does not decide it; a larger down payment can keep a loan conforming.
Many Lake Oswego homes sell above the point where a 20% down loan would exceed the conforming limit. You have three ways to handle it:
- A jumbo loan. Pricing can be competitive, sometimes close to conforming, but underwriting is stricter: expect a full review of income, assets and reserves (often six to twelve months of payments), and possibly two appraisals on very large loans. Frank's wholesale lenders include several jumbo specialists, and this is exactly where a broker's comparison pays off, because jumbo pricing varies widely between lenders.
- A larger down payment that brings the loan to $832,750 or less, so it prices and underwrites as conforming.
- A combination first and second mortgage (an 80/10/10 style structure) where the first stays conforming and a second lien covers part of the rest. Availability and pricing vary by lender.
Frank lays these out side by side with the total cost over the years you expect to keep the loan. The payment calculator flags when a scenario crosses the limit.
How do I buy my next Lake Oswego home before my current one sells?
Common options are a bridge or HELOC on the departing home, a loan that counts the pending sale, or qualifying with both payments. Which one works depends on your equity and income, and Frank can map it out before you make an offer.
Move-up buying is the norm in Lake Oswego, and sellers here rarely accept offers contingent on another sale in a strong market. Approaches Frank uses:
1. Qualify carrying both payments. Cleanest if your income supports it. Some lenders allow the departing home's payment to be excluded once it is under contract with contingencies removed. 2. Tap equity first. A home equity line of credit opened before listing can fund the down payment; it is paid off from the sale proceeds. Timing matters because many lenders will not open a HELOC on a listed home. 3. Bridge financing from a lender that offers it, typically short-term and more expensive, for buyers who need to close the purchase first.
Once your current home sells, the net proceeds calculator estimates what you will walk away with (Clackamas County has no transfer tax), and the "use these proceeds as my next down payment" link carries the figure into the affordability tools. A recast of the new mortgage after the sale can lower the payment without refinancing, if the lender allows it; ask Frank which of his lenders do.
Do lake easements, lakefront property and HOAs affect my loan?
They can. Lenders review HOA budgets and dues, lake easement associations count as HOAs for qualifying, and lakefront homes need appraisers with comparable sales, which can take longer. None of these are deal-breakers with the right lender.
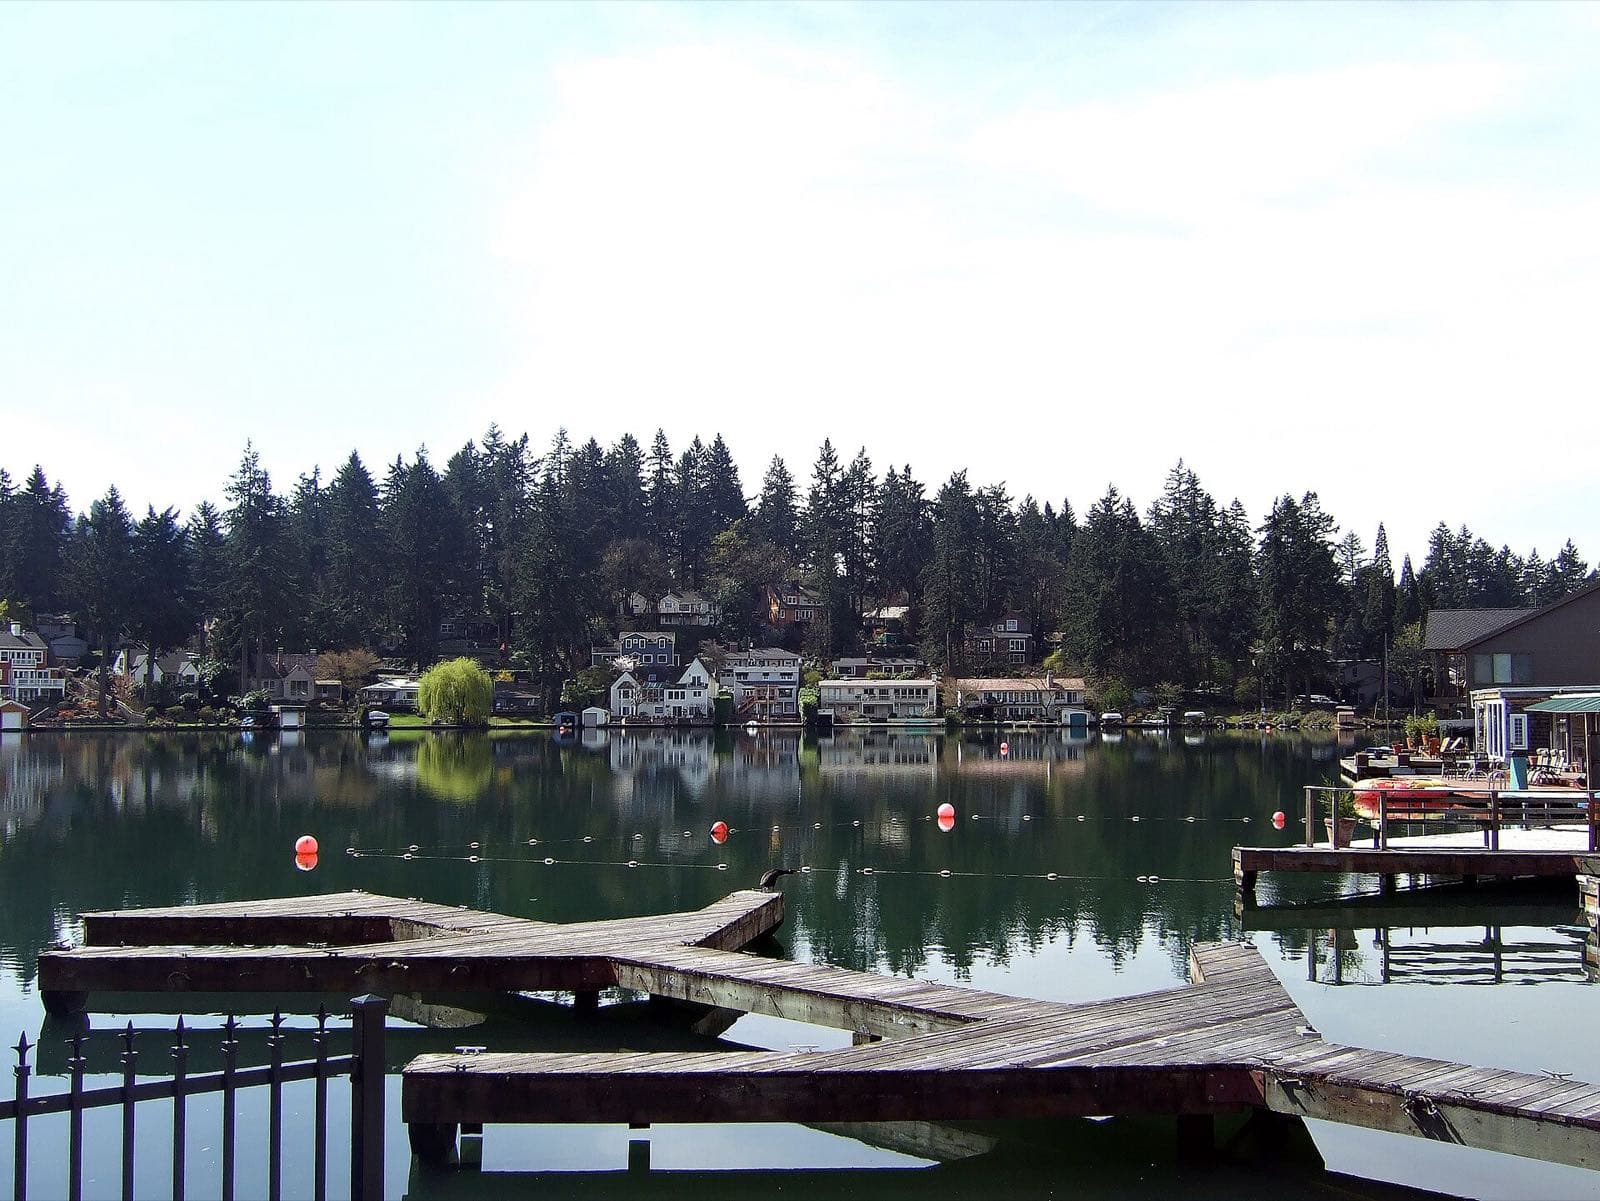
Oswego Lake is private, and access typically comes through a lake easement association tied to specific properties. For underwriting, an easement association's annual dues are treated like HOA dues: they count in your debt-to-income ratio and the lender may request the association's financial documents. Condominium and townhome purchases add a project review, and the lender checks the owners' association budget, reserves and any litigation.
Lakefront and view homes are harder to appraise because there are fewer comparable sales. Build extra time into the contract for the appraisal, and consider an appraisal gap plan if you are competing. Frank's lenders have local appraiser panels, and he will tell you up front which products require two appraisals at higher loan amounts.
Property taxes follow Oregon's Measure 50 rules, so the assessed value on a long-held Lake Oswego home is often well below market; use the actual Clackamas County tax statement when estimating escrow.
Is it worth paying points on a large loan?
Sometimes. On a jumbo loan, a point costs more in dollars but also saves more each month, so the break-even is roughly the same as on a smaller loan. The right answer depends on how long you will keep the loan.
A point is 1% of the loan amount, so on a $1,000,000 loan a point is $10,000. If it lowers the rate enough to save $150 a month, the break-even is about 67 months. Keep the loan longer than that and the point pays off; sell or refinance sooner and it does not.
Frank shows you each option in writing: the no-point rate, the rate with points, and the rate with a lender credit that reduces closing costs, each with the total cost over 5, 7 and 30 years. The buydown calculator runs the same math for permanent points and temporary buydowns. High-balance borrowers often prefer to keep cash invested and take a slightly higher rate; others prefer the lowest payment. Neither is wrong, and the comparison makes the trade-off visible.
Can I use a VA loan on a higher-priced Lake Oswego home?
Yes. With full entitlement there is no VA loan limit, so a veteran can finance a home above the conforming limit with no down payment if income and credit support the payment. Lenders may apply their own caps on very large VA loans.
Since 2020, veterans with full entitlement are not limited by the county loan limit. Residual income and debt-to-income still apply, and the VA funding fee, which is financed in most cases, grows with the loan amount. Veterans receiving VA disability compensation are exempt from the fee. If you have entitlement tied up in another VA loan, the county limit comes back into the math; the VA entitlement calculator walks through it. Full details are in the VA loans guide.
Can I meet Frank in person in Lake Oswego?
Yes, by appointment at Vantage's office on Pilkington Road. Most of the process, including the application, disclosures and Status Updates, happens online and by phone, which is faster, but an in-person meeting is available when it helps.
Frank sends detailed Status Updates at every milestone (application received, disclosures, appraisal, approval, clear to close, funded), so you always know where the loan stands. Start with a quick quote or call (208) 469-3340, and he will price your scenario across his lender network and show you the options side by side.
Financing a home in Oregon
Licensed in Washington, Oregon, and Idaho, helping homebuyers and homeowners explore financing for a wide range of loan programs and scenarios.
“I work with you to compare options from 35+ wholesale lenders competing for your loan.” Program details live on one page so they are always current; Frank walks you through the ones that fit your goals.
This page is general education, not a loan offer. Estimate only. This is not a Loan Estimate and not a commitment to lend. Your actual rate, payment and costs depend on your credit, the property and the loan program. Taxes and insurance are estimates. Program rules change; your loan officer will confirm current guidelines for your situation.
Run your own numbers
What clients say about working with Frank
“Frank and his team were responsive, professional yet friendly, and quite knowledgeable. Frank gave us options for our mortgage that we didn't know we had. Our loan process was so easy with Frank and his team!”
“We have worked with Frank for years. We continue to work with Frank and his team of specialists because they are thorough, efficient and professional.”
Source: Frank’s Client Reviews page on Vantage Mortgage Brokers’ website. Read all reviews.
Related guides
- Portland Mortgage Broker: Home Loans Across the Portland MetroBuying or refinancing in Portland: how Oregon's Measure 50 keeps assessed value below market value, Portland Housing Bureau down payment assistance, no transfer tax in Multnomah County, and how an independent broker compares lenders for you.
- Beaverton Mortgage Broker: Home Loans in Washington CountyBuying or refinancing in Beaverton: Washington County's $1 per $1,000 transfer tax (the only one in Oregon), qualifying on tech salaries with RSUs and bonuses, condos and townhomes, and how an independent broker compares lenders for you.
- Bend Mortgage Broker: Second Homes, Vacation Rentals and Central Oregon LoansFinancing in Bend and Deschutes County: second home vs. investment occupancy, short-term rental permits and DSCR loans, wildfire insurance availability, winter appraisal timing, and how an independent broker compares lenders.
Sources
- FHFA: Conforming loan limit values (opens in a new tab)
- Clackamas County Assessment & Taxation (opens in a new tab)
- Oregon Department of Revenue: Property tax (opens in a new tab)
- Oregon Department of Revenue: Maximum Assessed Value Manual (Measure 50) (opens in a new tab)
- VA.gov: VA home loan entitlement and limits (opens in a new tab)
- VA.gov: VA funding fee and closing costs (opens in a new tab)
- Fannie Mae Selling Guide (opens in a new tab)
- CFPB: Loan Estimate explainer (opens in a new tab)