
Related video
The Appraisal Process
What the appraiser does and what happens if the value comes in low.
Watch on its own pageHow can I buy my next home before I sell my current one?
Common options include qualifying with both payments, using a bridge loan or home equity line of credit for the down payment, or making an offer contingent on your sale. Each has trade-offs in cost and competitiveness.
Move-up buyers often have equity locked in their current home. Approaches include:
- Carry both payments. If your income supports both housing payments, you can buy first and sell later. Lenders count the current home's full payment unless it is sold, under contract with contingencies cleared, or documented as a rental.
- HELOC on your current home. Opening a home equity line before listing can fund the next down payment. It must be opened before the home is listed for sale, since most lenders won't open a line on a listed property.
- Bridge loan. A short-term loan secured by your current home, repaid when it sells. Bridge loans are less common and usually cost more.
- Sale contingency. Simpler financially, but sellers in competitive markets may prefer non-contingent offers.
Frank can model the payment and qualifying impact of each option. Any scenario is an estimate only, not a commitment to lend.
When does a Poulsbo purchase require a jumbo loan?
When the loan amount exceeds the county's conforming loan limit set annually by FHFA. For 2026, the baseline one-unit limit for most of the country is $832,750; check FHFA's table for Kitsap County.
Loans above the conforming limit cannot be sold to Fannie Mae or Freddie Mac, so they follow each lender's jumbo guidelines. Jumbo loans typically require stronger credit, larger reserves, and sometimes two appraisals for higher loan amounts. Pricing varies a lot from lender to lender, which is where shopping through a broker can matter.
Alternatives to a full jumbo include putting more down to stay under the conforming limit, or (where a lender offers it) pairing a conforming first mortgage with a second mortgage. Compare the blended cost of each approach rather than the first-mortgage rate alone. Current limits are on FHFA's conforming loan limit page (opens in a new tab).
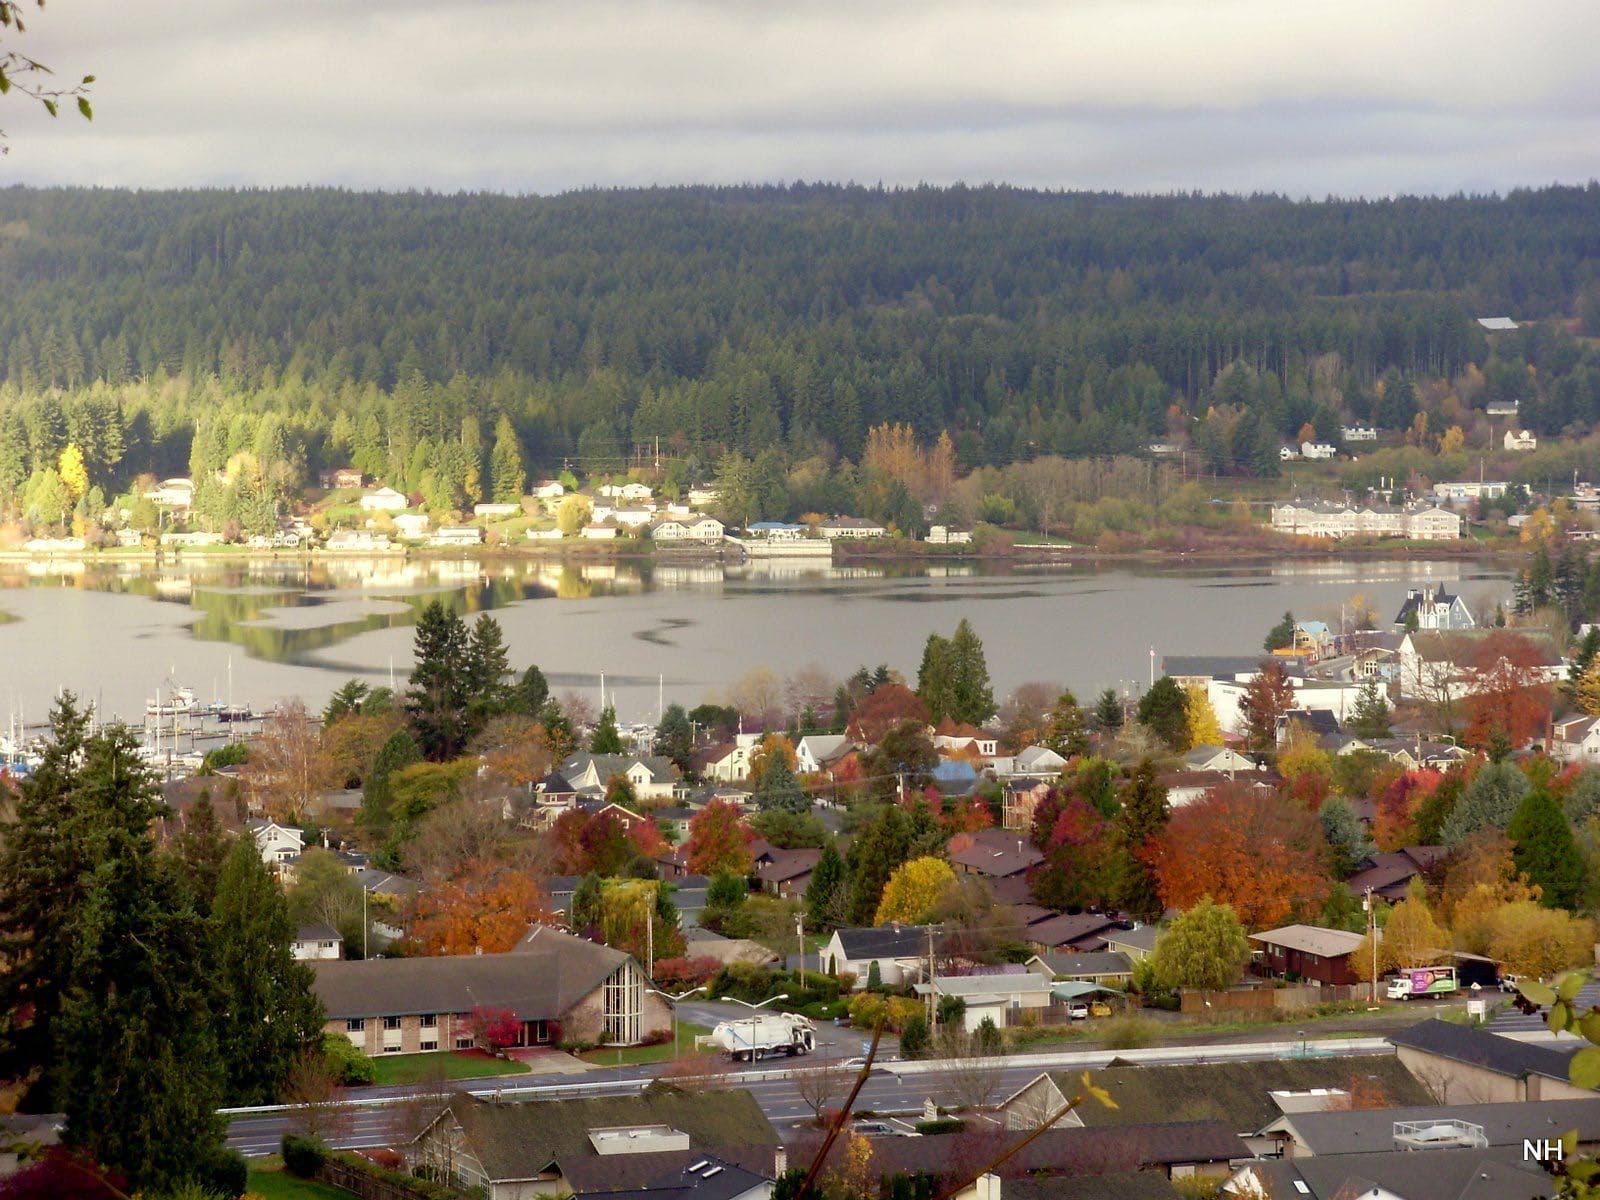
What do lenders look for on waterfront homes around Liberty Bay and Hood Canal?
Waterfront homes get closer appraisal and insurance scrutiny: comparable sales can be scarce, flood zone status determines whether flood insurance is required, and bulkheads, docks, and shoreline structures may be noted by the appraiser.
Points to plan for:
- Flood insurance. If any part of the home sits in a FEMA Special Flood Hazard Area, federally backed lenders require flood insurance. Get a quote before you're under contract; it affects your payment and qualifying.
- Appraisal. Waterfront comparables in Poulsbo and on Hood Canal can be few and far apart in time and distance. A low appraisal is more likely, so build some flexibility into your offer.
- Septic and water. Many waterfront homes outside city limits rely on septic systems; some use private or shared wells. Lenders and inspectors may want testing.
- Shoreline structures. Docks and bulkheads can add value but also maintenance and permitting considerations.
Can rural North Kitsap homes with wells and septic be financed normally?
Yes. Conventional, FHA, VA, and USDA loans all finance homes with private wells and septic systems, though some programs require water testing, and shared wells usually need a written maintenance agreement.
Requirements vary by loan program and by lender. FHA and VA have specific water-quality and distance guidelines between wells and septic drainfields; conventional loans rely more on the appraiser and local health requirements. Homes on private or shared roads may need a recorded road maintenance agreement or easement showing legal access.
Parts of North Kitsap outside urban growth areas may also be eligible for USDA guaranteed loans, which require no down payment for eligible borrowers in eligible areas. Check the USDA eligibility map (opens in a new tab).
How is retirement income counted when I'm buying in Poulsbo?
Pension, Social Security, and military retirement income generally count if they are documented and expected to continue for at least three years. Retirement account withdrawals can also be used under specific rules.
Lenders usually document retirement income with award letters and bank statements. Non-taxable income, such as some Social Security and VA disability compensation, can often be "grossed up" for qualifying, which can increase how much it counts. Retirees with substantial savings but modest monthly income may be able to use distributions from retirement accounts or an asset-depletion approach, depending on the program and lender.
Military retirees can also use their VA benefit for a Poulsbo purchase; see the Kitsap County VA loan guide.
What's the next step?
Gather income and asset documents, get a pre-approval that reflects your plan for your current home, and compare current pricing.
See today's pricing on the live rates page, estimate payments with the mortgage payment calculator, or schedule a call to talk through a move-up plan. Nearby guides: Silverdale and the county-wide Kitsap County mortgage broker page.
Financing a home in Kitsap County
Licensed in Washington, Oregon, and Idaho, helping homebuyers and homeowners explore financing for a wide range of loan programs and scenarios.
“I work with you to compare options from 35+ wholesale lenders competing for your loan.” Program details live on one page so they are always current; Frank walks you through the ones that fit your goals.
This page is general education, not a loan offer. Estimate only. This is not a Loan Estimate and not a commitment to lend. Your actual rate, payment and costs depend on your credit, the property and the loan program. Taxes and insurance are estimates. Program rules change; your loan officer will confirm current guidelines for your situation.
Run your own numbers
What clients say about working with Frank
“Frank and his team were responsive, professional yet friendly, and quite knowledgeable. Frank gave us options for our mortgage that we didn't know we had. Our loan process was so easy with Frank and his team!”
“We have worked with Frank for years. We continue to work with Frank and his team of specialists because they are thorough, efficient and professional.”
Source: Frank’s Client Reviews page on Vantage Mortgage Brokers’ website. Read all reviews.
Related guides
- Kitsap County: Puget Sound living with the Olympics out the windowGet to know Kitsap County: Naval Base Kitsap and its military community, Olympic Mountain views, the waterfront towns of Silverdale, Bremerton, Poulsbo, Port Orchard, Bainbridge Island and Kingston, ferries to Seattle, and what living here is like. Financing guidance from Frank Ellerbroek, an independent mortgage broker with deep Kitsap roots.
- Silverdale Mortgage Broker: Financing a Home Near Bangor and Central KitsapFinancing a home in Silverdale, WA: buying on PCS orders, new-construction and HOA communities, condos and townhomes, rent-vs-buy for short tours, and comparing lenders.
- Kitsap County VA Loans: A Practical Guide for Service Members and VeteransA plain-English guide to VA home loans in Kitsap County: zero down with full entitlement, residual income, seller concessions, reusing your entitlement, 2 to 4 unit homes, and VA appraisals.
- Bremerton Mortgage Broker: Financing Older Homes, Condos, and Shipyard CareersFinancing a Bremerton home: shipyard and civilian Navy income, older homes and appraisal repairs, renovation loans, downtown condos near the ferry, and small multi-family properties.
Sources
- FHFA: Conforming loan limit values (opens in a new tab)
- Fannie Mae Selling Guide (opens in a new tab)
- Fannie Mae Selling Guide B2-2-03: Multiple Financed Properties for the Same Borrower (opens in a new tab)
- Freddie Mac Single-Family Seller/Servicer Guide (opens in a new tab)
- HUD Single Family Housing Policy Handbook 4000.1 (opens in a new tab)
- USDA: Property eligibility map (opens in a new tab)
- CFPB: Loan Estimate explainer (opens in a new tab)